premiums in 2027
Key points at a glance
Here you’ll find all the details on our premiums, along with useful background information and handy tips.
Basic insurance
Sanitas is one of the most affordable health insurers in 21 regions
Health insurance premiums in Switzerland will need to rise again in 2027 due to the continued increase in healthcare costs – for example, as a result of higher spending on visits to the doctor, treatments and medicines. But why are healthcare costs rising, and what can we do about it? Find out more here.
As a result, Sanitas cannot avoid raising premiums either. The average increase at Sanitas is 3.8%, which is below the market average. Sanitas therefore remains the right choice for you in the coming year.
These factors affect your basic insurance premium
Premium region
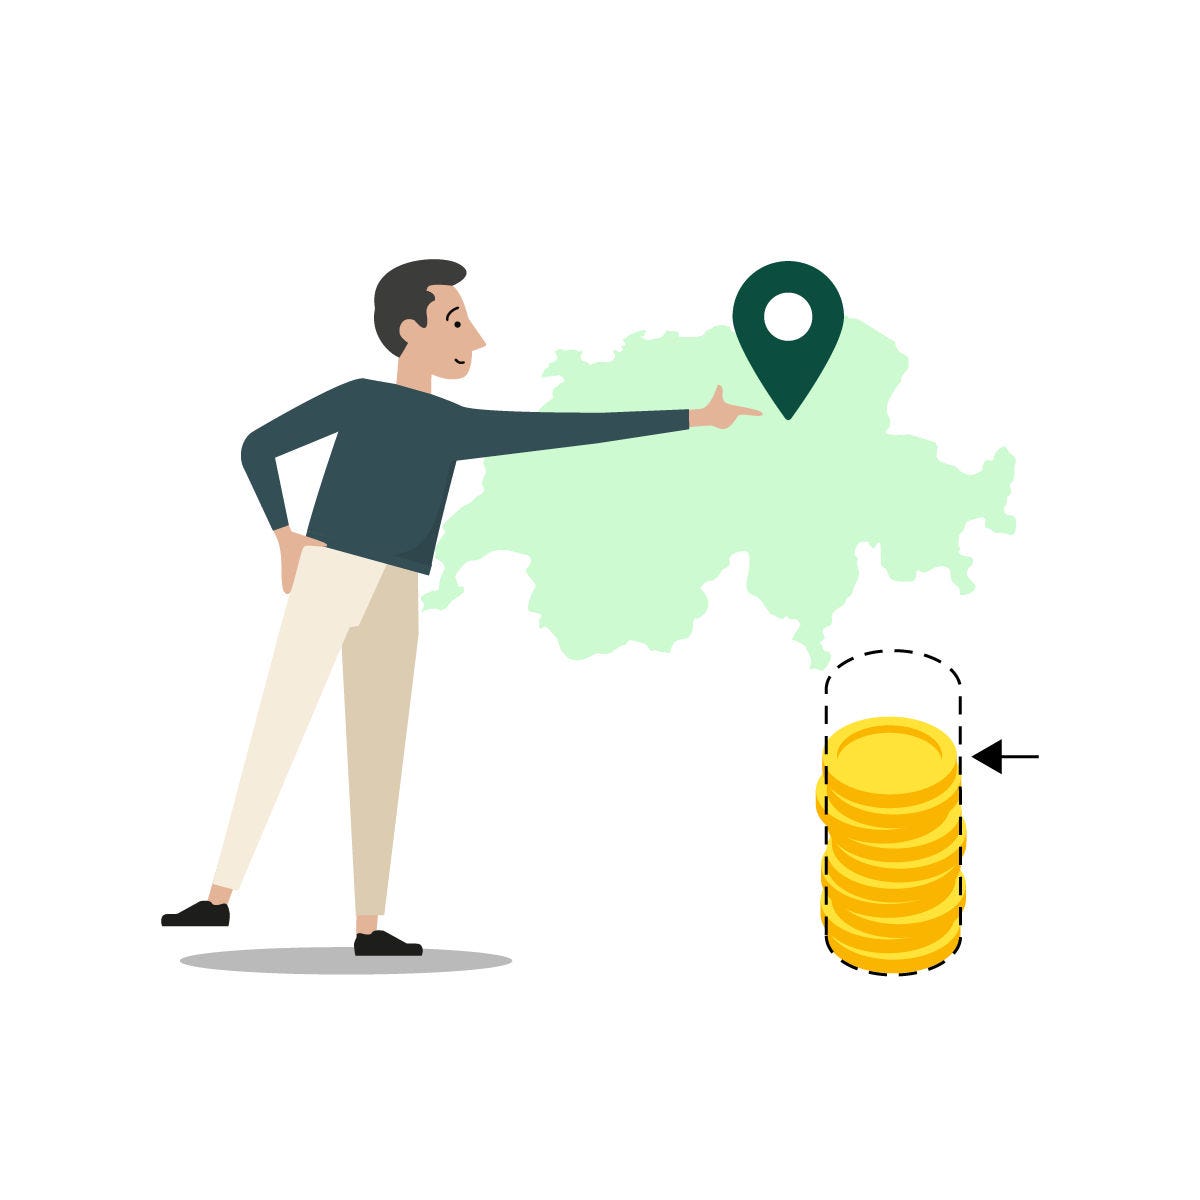
Your health insurance premium is influenced by several factors, including the premium region in which you live. For example, healthcare costs are generally higher in urban areas than in rural regions.
Insurance model
With an alternative insurance model for basic insurance, you benefit from discounts and a central point of contact for health queries – for example your long-standing family doctor or the telemedicine centre.
Age group
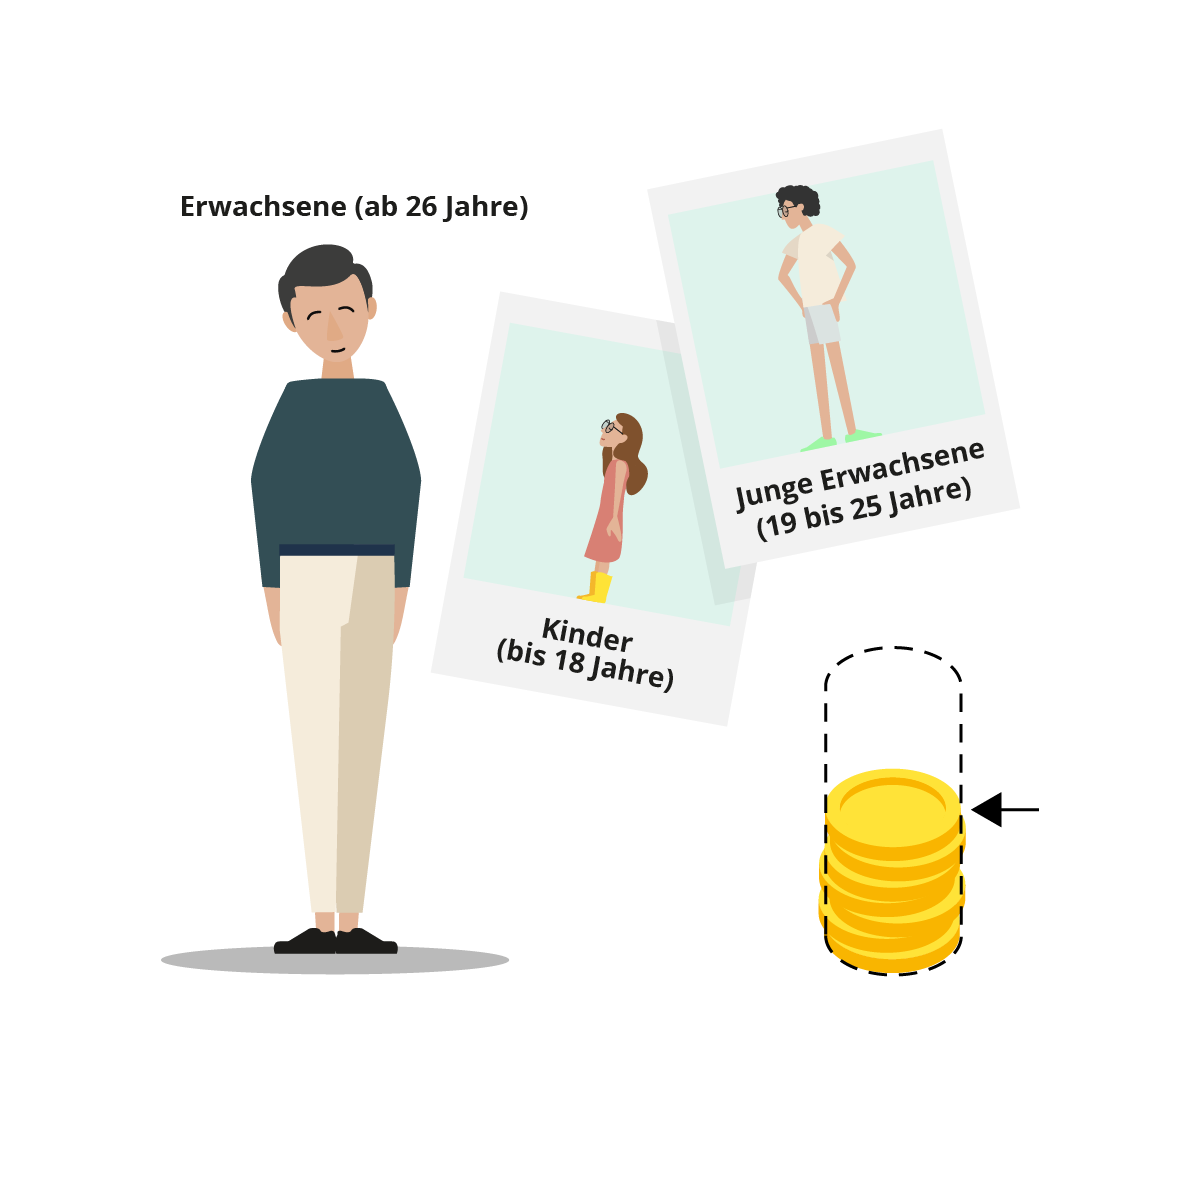
There are three age groups defined by law: children (up to age 18), young adults (age 19 to 25) and adults (age 26 and older). When you move into a new age group, your premium will increase.
Elective deductible
By choosing a higher deductible, you can save money on premiums, but you also bear a greater financial risk in case of illness.
Discounts for alternative insurance models
All basic insurance models provide the same benefits. The main difference lies in who you have to contact first if you have health queries. The more effectively a model reduces costs through optimised treatment pathways, the greater the premium discount compared with the standard model.


Supplementary insurance
Good news for many customers with supplementary insurance
The good news is that premiums for most of our supplementary insurance plans will remain stable. Any adjustment will depend on the product line and the specific insurance plan.
-
Premiums for supplementary insurance
The premiums of these popular Sanitas supplementary and supplementary hospital insurance plans will remain stable in 2027 (list not exhaustive):
Customers with the following supplementary insurance plans will continue to benefit from a discount on their monthly premium (list not exhaustive):
Medical Private 10% discount (unchanged) Hospital Day Comfort 25% discount (new)
Hospital Top Liberty
15% discount (unchanged) Non-listed hospitals 15% discount (unchanged)
Corporate Hospital Top 10% discount (unchanged) Corporate Hospital Standard 10% discount (unchanged) The monthly premium will increase for these supplementary insurance plans (list not exhaustive):
Vital Premium increase ranging from just under CHF 2 to CHF 10 per month The monthly premium will decrease for these supplementary insurance plans (list not exhaustive):
Deadlines and periods of notice
-
Change the deductible for basic insurance
- Your deductible can only be changed with effect from 1 January of the following year.
- If you want to reduce your deductible, we must receive notification by 30 November 2026 (last working day in November).
- If you want to increase your deductible, we must receive notification by 30 December (last working day in December).
In the Sanitas Portal, you have until 30 November to reduce your deductible and until 31 December to increase it.
- Your deductible can only be changed with effect from 1 January of the following year.
-
Transfer to an alternative insurance model
Would you like to switch from basic insurance with free choice of doctor to an alternative insurance model? You can do so at the beginning of any month. If you are already insured under an alternative insurance model and would like to switch to a different one, you can only do so as of 1 January of the following year. In this case, we must receive your notification by 30 November 2026 (last working day in November).
Here you can find an overview of all our alternative insurance models.
-
Terminating basic insurance
Switching health insurer with effect from 1 January: Your current health insurer must receive your notice of termination by 30 November 2026 (last working day in November) at the latest. Simply fill out the termination form below and send it to your current health insurer.
Switching health insurer with effect from 1 July: If you have the lowest deductible with your current health insurer (adults: CHF 300, children: CHF 0) and the standard model with free choice of doctor (no family doctor, network or telemedicine model), you can switch health insurers effective 1 July. Your current health insurer must receive your notice of termination by 31 March 2027 (the last working day in March) at the latest.
-
Terminating supplementary insurance
You can take out and terminate supplementary insurance plans independently of basic insurance.
Deadlines for termination vary depending on the health insurer. Please check the deadlines with your current health insurance provider and only cancel your current supplementary insurance when you have received confirmation of admission from Sanitas.
-
Premium debts of parents
Under basic insurance: Up to the end of the month in which the young adult turns 18, their parents are responsible for paying their health insurance bills. Even after that, young adults are not liable for invoices dating back to before their 18th birthday. However, from the month following their 18th birthday, young adults are responsible for paying their own health insurance bills. If all invoices are paid on time starting on the first day of the month following their 18th birthday, the insured person may switch health insurer subject to the valid period of notice.
Practical guides


900 000 satisfied customers


Frequently asked questions
-
When will I receive my first premium invoice for the new year?
You will receive your new premium invoice at the start of December 2026.
-
Why are my premiums suddenly higher?
In addition to rising healthcare costs, your age can also affect your premiums. For basic insurance, two age group transfers (at age 19 and 26) are prescribed by law. For supplementary insurance, age group transfers are customary every 5 years with many health insurers.
-
What is Sanitas doing against high premiums?
Increasing health costs are causing premiums to rise. That’s why we offer a number of offers and measures to help keep healthcare costs under control. These include digital offers that provide rapid help in the event of illness and avoid unnecessary visits to the doctor or incorrect treatment. We also offer preventive services to support a healthy lifestyle. After all, prevention is always better than cure – from a financial perspective too.
Find out more here.
-
Why aren’t premiums the same for all health insurers?
It’s true that basic insurance premiums for Sanitas and other health insurers can differ. The reason for this is that insurance companies have to calculate premiums independently of each other. This is prescribed by law and monitored by the supervisory authority, the Federal Office of Public Health.
Premiums primarily reflect a health insurer’s cost of claims (e.g. doctor and hospital invoices). Each health insurer has to calculate the premiums for each premium region. The premiums must cover the costs arising from the insured persons in each premium region. As costs per region and per insurance company differ depending on the customer base, this can lead to different premiums.
-
What is a premium subsidy and who pays it?
The premium subsidy or health insurance subsidy provides financial support for basic insurance premiums. It helps people whose annual income and assets fall below a specific threshold. The federal government provides the cantons with funds for these premium subsidies.
In most cantons, subsidies are granted automatically based on the tax assessment. However, in some cantons you have to submit an application to the responsible authority. In most cases, applications must be received by a specific deadline. We recommend that you get in touch with the responsible authority in your canton or municipality of residence in good time to discuss the procedure.
You can find a list of the relevant cantonal authorities here.
-
Who is entitled to a premium subsidy?
Individuals, married couples and families whose annual income and assets fall below a specific threshold are entitled to a premium subsidy. Eligibility is regulated by the cantons. In many cantons, eligible individuals are informed directly, while in some cantons, they must submit an application.
We recommend that you get in touch with the authority in your canton or municipality of residence to discuss the procedure. You can find a list of the relevant cantonal authorities here.
-
Can I terminate my health insurance by phone?
No. You have to terminate your health insurance in writing. All health insurers accept notice of termination by post. Some insurers – including Sanitas – also accept notice of termination by email. Please contact your current health insurer for more information. In all cases, all persons of legal age affected have to sign the relevant notice of termination. Important: Only terminate your supplementary insurance once you have received confirmation of admission from your new health insurer.
Termination form for basic insurance
-
Can I just change my basic insurance and keep my supplementary insurance?
Yes. You can take out and terminate basic insurance plans independently of supplementary insurance. Simply note your wish on the termination letter to your health insurance company.
-
When will I receive my new insurance card?
Your insurance card will be sent to you by post. It can take up to six weeks for your card to arrive. If you need your insurance card to buy medicines or receive medical treatment in the meantime, you can give your customer number to your doctor, therapist or pharmacist.
Tip: you always have your insurance card to hand with the Sanitas Portal.
-
Why do I get environmental levies back?
In Switzerland, there is an environmental levy on climate-damaging CO2 emissions (CO2 levy) and another on environmentally harmful components in solvents (VOC levy). These levies aim to encourage more economical use of harmful substances, which benefits the climate and our health. Some of the environmental levies are redistributed to the population via health insurance. This approach was chosen to keep administrative costs low. Another portion of the revenue from CO2 levies is specifically invested in climate protection projects.
-
*Premium discounts
*Family Doctor: Discount of between 7% and 18%
Example of 7% discount: Adult premium for Family Doctor compared to Free Choice of Doctor (Aargau, CHF 300 deductible, with accident cover)
Example of 18% discount: Adult premium for Family Doctor compared to Free Choice of Doctor (Zug, CHF 2,500 deductible, with or without accident cover)*MultiAccess: Discount of between 9% and 13%
Example of 9% discount: Adult premium for MultiAccess compared to Free Choice of Doctor (Aargau, CHF 300 deductible, with accident cover)
Example of 13% discount: Adult premium for MultiAccess compared to Free Choice of Doctor (Zug, CHF 2,500 deductible, with or without accident cover)*TelMed Plus: Discount of between 7% and 11%
Example of 7% discount: Adult premium for TelMed Plus compared to Free Choice of Doctor (Aargau, CHF 300 deductible, with accident cover)
Example of 11% discount: Adult premium for TelMed Plus compared to Free Choice of Doctor (Zurich 1, CHF 2,500 deductible, with or without accident cover)TelMed Basic: Discount of between 10% and 20%
Example of 10% discount: Adult premium for TelMed Basic compared to Free Choice of Doctor (Ticino 2, CHF 300 deductible, with accident cover)
Example of 20% discount: Adult premium for TelMed Basic compared to Free Choice of Doctor (Zurich 1, CHF 2,500 deductible, with or without accident cover)